For Those Approaching Retirement (5–15 Years Out)

Can You Actually Afford to Retire When You Want?

After 30+ years of work, you deserve concrete answers about retirement, not vague reassurances.

CFP® Certified
30+ Years Experience
In-Person & Virtual
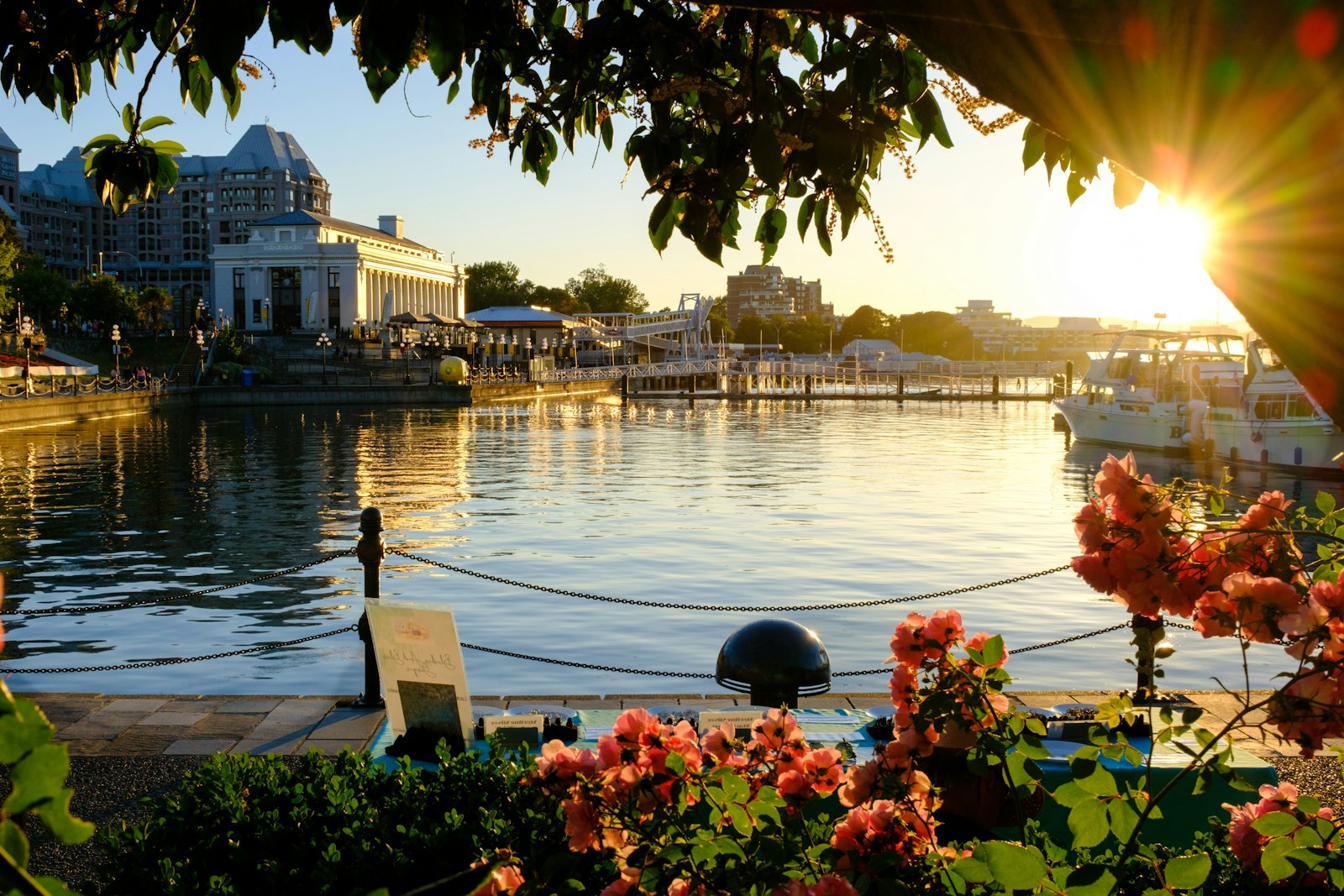
Victoria, BC harbour at sunset - the kind of life DesignWealth helps clients retire into
6 Months
100% money-back guarantee on planning

Only 15% of Canadian retirees stopped working because they had saved enough. A clear plan helps you know what is actually possible for you - and when.Manulife Financial Resilience and Longevity Report, 2025. Survey of 514 retired Canadians, May 2025.

The Questions Keeping You Up

Retirement Should Excite You, Not Terrify You

When Can I Actually Retire?

Don't guess. Know your exact retirement date based on your specific numbers, not industry averages.

Will My Money Last?

Plan to age 90+ with confidence, not anxiety. Know exactly how much you can safely spend each year.

CPP at 60, 65, or 70?

A single decision worth $40K–$80K over your lifetime. The optimal answer depends on factors most people never consider.

What About Healthcare?

The expense nobody plans for until it's too late. If healthcare costs are a concern for you, we can absolutely model those into your retirement plan.

Your Retirement, Planned to the Dollar

Your Plan Leads. The Right Tools Make It Work.

For planning clients, we build your retirement plan first - with specific dates, exact numbers, and contingency scenarios. Then we coordinate your investments and coverage so every piece supports the retirement you've earned. Investment guidance and insurance are also available on their own if a full financial plan is not what you're looking for right now.

Retirement Readiness Assessment

Get a specific retirement date, not an estimate.

CPP/OAS Optimization

The right CPP and OAS start dates can be worth tens of thousands of dollars over a lifetime. We help you find the optimal timing for your specific situation.

Tax-Efficient Withdrawal Strategy

Pay less tax in retirement through careful sequencing of RRSP, TFSA, and non-registered withdrawals.

Estate Planning Integration

Protect what you've built for your family with integrated estate and legacy planning.

Scenario Planning

See what happens if markets drop 30%, health changes, or your plans shift. Be prepared for anything.

Investment Reviews & KYC Updates

As retirement approaches, we review your investments regularly to ensure they support your income needs and long-term goals - without abandoning growth entirely.

Retirement Income Portfolio

We help coordinate your retirement income sources - including RRIF conversions, dividend strategies, and drawdown timing - so your money works together to sustain the lifestyle you have planned.

Insurance & Beneficiary Reviews

Ensure your coverage still fits your needs and that your beneficiary designations align with your estate plan.

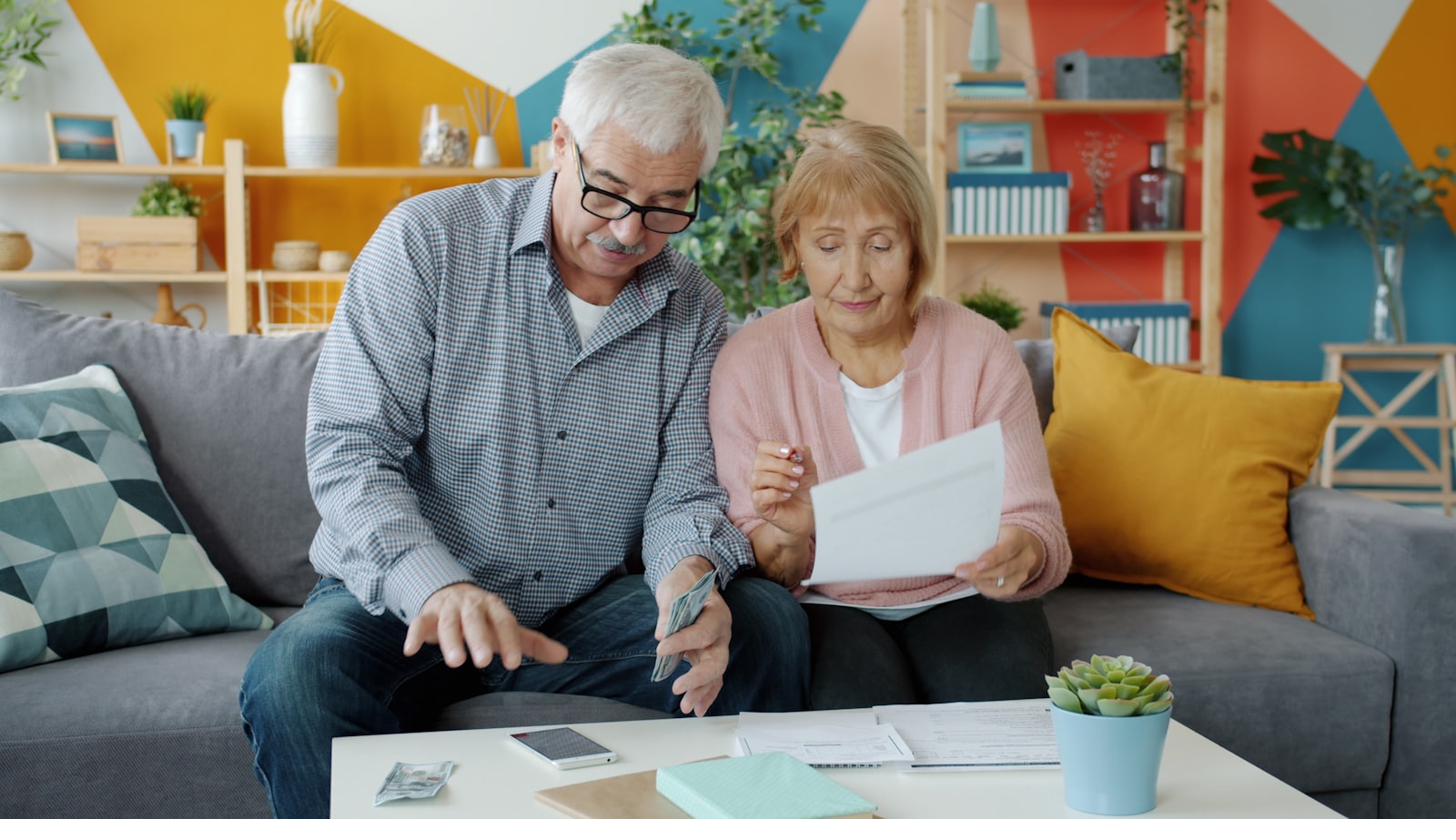
Couple reviewing their retirement plan together at home
Client Success Story

How the Richardsons Retired 3 Years Early

At 58, they thought they needed to work until 65. After CPP/OAS optimization, an RRSP bridge strategy, and comprehensive tax planning, they discovered they could retire at 62 with full confidence - and more annual income than they expected.

3 years
Earlier retirement
$73K
Additional lifetime CPP income
24 years
of planning fees covered by CPP optimization alone
Myth vs. Reality

The $1M Retirement Myth

You've heard you need $1 million to retire. But the truth is, there's no universal number. What YOU actually need is personal - and it depends on:

  • Your home equity and mortgage status
  • Whether you have a pension
  • Your planned retirement lifestyle
  • CPP/OAS optimization strategy
  • Downsizing or relocation plans
  • Your investment mix and income needs
  • Insurance coverage and healthcare costs
Find Your Retirement Number
$1,000,000
YOUR Number

We build your personalized income plan showing what you actually need - based on your life, your goals, and your numbers.

Financial Certainty Score

Eight questions. Under two minutes.

Not a test of whether you have saved enough. A quick check on how much of your retirement you could describe in specifics.

From Clients Approaching Retirement

Client Stories

★★★★★

"We discovered we could retire 3 years earlier than we thought. Having a concrete plan instead of guesswork changed everything for us."

SR
S. & T. R.
Retired Couple, Victoria
★★★★★

"The CPP timing analysis alone was worth years of planning fees. I had no idea a single decision could be worth $73K over my lifetime."

DM
D. M.
Government Employee, Victoria

Common Questions About Approaching Retirement

How far in advance should I start planning for retirement?
Ideally, 10-15 years before your target retirement date. However, even 5 years out, there are significant optimization opportunities. The sooner you start, the more time we have to determine the optimal timing for CPP and OAS, optimize tax strategies, and ensure your investments are positioned for the transition ahead.
I have a pension - do I still need a financial planner?
Absolutely. A pension is one piece of your retirement income puzzle. Coordinating pension income with CPP/OAS timing, RRSP drawdowns, and TFSA withdrawals requires careful planning to minimize taxes and maximize total income. Many pension holders leave tens of thousands on the table by not coordinating these sources.
What's the optimal age to start CPP?
It depends on your health, other income sources, spouse's CPP timing, and tax situation. There's no universal "right" answer. Delaying from 65 to 70 increases your benefit by 42%, but bridging that gap requires strategy. We model multiple scenarios to find your optimal timing.
How do you handle couples with different retirement timelines?
This is extremely common and requires coordinated planning. We model both partners' retirements together as a unified plan - not separately. The goal is to ensure both timelines are addressed and the transition works for the couple as a whole, not just each individual in isolation.
Can you help with estate planning?
Yes. While we don't draft legal documents (that's your lawyer's role), we integrate estate planning into your overall financial plan - including beneficiary optimization, tax-efficient wealth transfer strategies, and ensuring your wishes are financially supported. We are happy to work alongside your legal team where it makes sense.
Your Next Step

Your Retirement Clarity Starts Here

No obligation. No pressure. Just answers to the questions that matter most about your retirement.